Best Credit Cards for Buying a Car in India in 2026

Buying a car is already a big expense. So if you’re spending ₹10 lakh, ₹15 lakh or even more, it is normal to wonder if you can get some extra benefit by paying with a credit card.
The answer is sometimes yes.
But there is one thing I would check before getting too excited about the reward points.
Will the dealer actually accept your credit card, and will the payment earn rewards?
Some dealers don’t accept credit cards for the full car payment. Others may accept it but charge an extra fee. And even when the payment goes through, you should not assume that every card will give you rewards on that transaction.
So, if you’re planning to buy a car in 2026, here are the cards I’d look at — especially if you already have one of them.
First, check with the car dealer
This is probably more important than choosing the card.
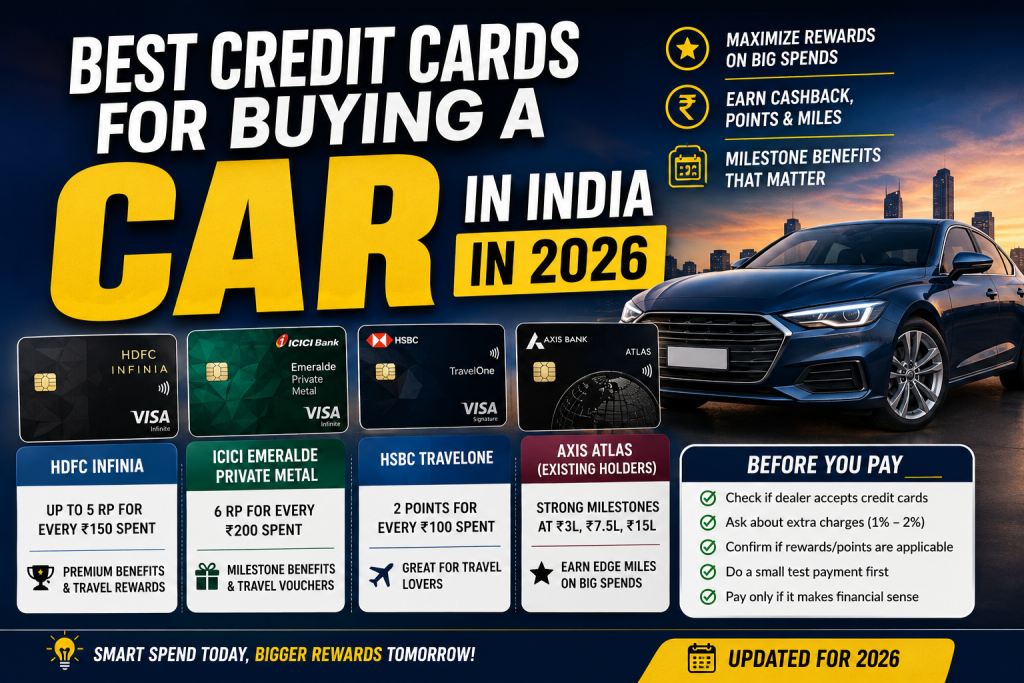
Before you make a ₹10 lakh or ₹15 lakh payment, simply ask the dealer:
“Can I pay the car amount by credit card?”
Then ask:
“Is there any extra charge for card payment?”
This matters because even a 1.5% charge on ₹10 lakh is ₹15,000.
So getting ₹20,000 worth of rewards doesn’t look very impressive if you had to pay ₹15,000 extra for using the card.
I’d also ask whether the entire amount can be paid by card or only the booking amount.
And one more thing — ask how the transaction will be processed. The merchant category used by the dealer can affect whether a card gives rewards.
Basically, don’t assume. Check first.
1. HDFC Infinia
If you already have HDFC Infinia, this is one of the cards I’d seriously consider for a large purchase.
It is a premium card and is generally aimed at high spenders. HDFC’s current information says regular retail spends earn 5 Reward Points for every ₹150 spent.
So, for a simple example, if a ₹15 lakh car payment is treated as an eligible retail transaction, the base reward earning can be meaningful.
But don’t blindly calculate the rewards before making the payment.
The important part is whether your particular car transaction qualifies.
I’d actually call the bank or confirm the merchant category before putting a huge amount on the card.
Why I like Infinia
The biggest advantage isn’t just the base reward rate.
It’s the overall package.
You get a premium rewards system, travel benefits and other features that can make the annual fee worthwhile if you actually use them.
And if you’re already an Infinia holder, you don’t need to apply for another card just because you’re buying a car.
My view: If you already have Infinia and the dealer accepts it without a silly surcharge, it’s worth checking the numbers.
2. ICICI Emeralde Private Metal
This is another card for people who are comfortable with premium credit cards.
ICICI currently lists the Emeralde Private Metal with a ₹12,499 joining fee and ₹12,499 annual fee. The bank also lists fee reversal based on annual spending, along with reward points and an ₹8 lakh milestone benefit that includes two EaseMyTrip vouchers worth ₹3,000 each.
So if you’re already eligible for this card and have a large purchase coming up, the car payment could potentially help you reach a spending milestone.
But again, don’t look only at the reward rate.
Look at the complete picture:
- How much is the card fee?
- Will the car payment earn points?
- Will the dealer charge you extra?
- Will the spending help you reach a milestone?
- Can you actually use the benefits later?
If the answer to most of these is yes, then it starts making sense.
If you’re taking the card only because you’re buying a car once, I’d think twice.
3. HSBC TravelOne
HSBC TravelOne is another interesting option, especially if you like travel rewards.
The card currently has a ₹4,999 joining/renewal fee, and its reward structure gives 2 points per ₹100 on regular spends, with higher earning on some travel-related spending.
HSBC also has a fairly large airline and hotel transfer programme. Its rewards programme includes partners such as Air India Maharaja Club, Singapore Airlines KrisFlyer, Etihad Guest, British Airways, Flying Blue and several hotel programmes.
Now, would I take this card only to buy a car?
Probably not.
But if you already wanted TravelOne for your normal spending and travel, a large eligible purchase could make the card more interesting.
Just don’t assume the car payment will automatically qualify for the same rewards as travel spending. A car purchase is still a car purchase.
Check the current terms before doing it.
4. Axis Atlas — Great for Existing Cardholders
Axis Atlas deserves a mention, but there is an important catch in 2026.
I wouldn’t recommend it to someone looking for a new card without first checking whether applications are actually available.
The card is particularly interesting for existing holders because of its EDGE Miles and milestone structure. Axis’s terms list milestones at ₹3 lakh, ₹7.5 lakh and ₹15 lakh of eligible spending.
So if you already have Atlas and you’re buying a ₹15 lakh car, the spending level is obviously interesting.
But there is a big difference between:
“I already have Atlas.”
and
“I want to get Atlas now.”
Don’t confuse the two.
The availability of the card for new applicants has changed, so check Axis’s current application status before making any plans around it. Current 2026 reporting also notes that fresh Atlas applications have been closed.
Also, Axis has changed parts of the Atlas reward structure over time, so old YouTube videos and articles can easily give you outdated information.
That’s one reason I always prefer checking the bank’s current terms before a big transaction.
5. A Good Premium Card You Already Have
This might sound strange, but sometimes the best card for buying your car is the card already sitting in your wallet.
You don’t necessarily need to apply for a new credit card.
Let’s say you already have a premium card with:
- a high enough credit limit
- good rewards
- no major issue with acceptance
- and a fee structure you understand
Why get another card just for one transaction?
For example, if your existing card gives you a decent reward rate and the dealer accepts it without an extra charge, it may be perfectly fine.
The internet can make it feel like you need a special credit card for every type of purchase.
You don’t.
What About Buying a ₹15 Lakh Car?
Let’s take a simple example.
Suppose the car costs ₹15 lakh.
You find a credit card that appears to give you around 3% in rewards.
On paper:
₹15,00,000 × 3% = ₹45,000
Sounds great.
But now suppose the dealer charges 1.5% for accepting the card.
That’s:
₹15,00,000 × 1.5% = ₹22,500
Now your ₹45,000 reward isn’t really a ₹45,000 benefit.
The actual gain is much smaller.
And that’s before considering whether the transaction actually earns the rewards you expected.
This is why I wouldn’t look at the reward percentage alone.
Don’t Pay the Whole Amount Without Checking
This is something I’d personally do.
If the dealer allows a small booking payment by credit card, you can first check how the transaction appears on your statement.
For example, don’t immediately put the entire ₹15 lakh on the card if you’re unsure whether it qualifies for rewards.
Make a smaller eligible payment first, if the dealer allows it, and then check the transaction.
You can also confirm with the card issuer.
It takes a little extra time, but that’s better than finding out after a ₹15 lakh payment that the reward points weren’t applicable.
What If the Dealer Charges 1% or 2%?
Then do the maths.
Don’t just think:
“I’m getting rewards, so it’s free money.”
It’s not.
For example, if you get 3% value but pay 2% as a card-processing charge, your real benefit is much lower.
And there may be taxes or other charges depending on how the payment is processed.
Sometimes paying by bank transfer or cheque is simply better.
There is nothing wrong with that.
The purpose of a credit card is to save or earn something useful — not to use it at any cost.
Should You Use a Credit Card for the Down Payment?
You can consider it if the dealer accepts the payment and the numbers work.
But I’d be careful here.
If you are already stretching your budget to buy the car, don’t put a large amount on a credit card just because you want reward points.
A credit card bill is still a bill.
If you cannot pay the full amount when the statement comes, the interest can wipe out the value of your rewards very quickly.
So don’t borrow ₹10 lakh on a credit card for the sake of earning ₹30,000 in points.
That makes no sense.
What I Would Do
If I were buying a car and wanted to use a credit card, I’d keep it pretty simple.
First, I’d ask the dealer if they accept credit cards.
Then I’d ask about the extra charge.
After that, I’d check the card’s current reward terms.
Then I’d make sure the transaction is actually eligible for rewards.
And finally, I’d check whether the credit limit is high enough without causing any other problem.
If everything looks good, I’d use the card.
If the dealer wants a big extra fee, I’d probably skip it.
Which Card Is Best?
There isn’t one card that is automatically best for every car buyer.
If you already have HDFC Infinia: I’d check this first because of its strong base reward structure and premium benefits.
If you already have ICICI Emeralde Private Metal: Check the reward and milestone benefits against the dealer’s charges. The ₹8 lakh milestone can be useful if you can actually use the vouchers.
If you like travel rewards: HSBC TravelOne is worth looking at, especially if you will use the card for travel after buying the car.
If you already have Axis Atlas: It can be interesting because of its milestone structure, but check the latest terms and your current card status first.
If you have a good card already: Don’t feel pressured to get another one.
One Last Thing
I’d avoid choosing a credit card only because you’re buying a car.
A car is a one-time or occasional purchase. Your credit card will stay in your wallet for much longer.
So choose a card that makes sense for your normal spending too.
If you travel, get something useful for travel.
If you shop a lot, look at shopping rewards.
If you mainly use UPI and everyday payments, you may not need an expensive premium card at all.
The car purchase can be a nice bonus opportunity, but it shouldn’t be the only reason you get a card.
Final Verdict
Yes, buying a car with a credit card can be rewarding.
But don’t get distracted by a big reward number.
Check the dealer first. Check the card terms. Check the extra charges. Then do the maths.
For a ₹10 lakh or ₹15 lakh purchase, even a small processing fee can make a big difference.
And most importantly, only use the credit card if you can comfortably pay the bill in full.
A few thousand rupees of rewards are not worth getting stuck with expensive credit-card debt.
Credit-card fees, reward rules, eligibility and merchant conditions can change. Always check the latest terms with the card issuer and confirm the payment charges with your car dealer before making a large transaction.